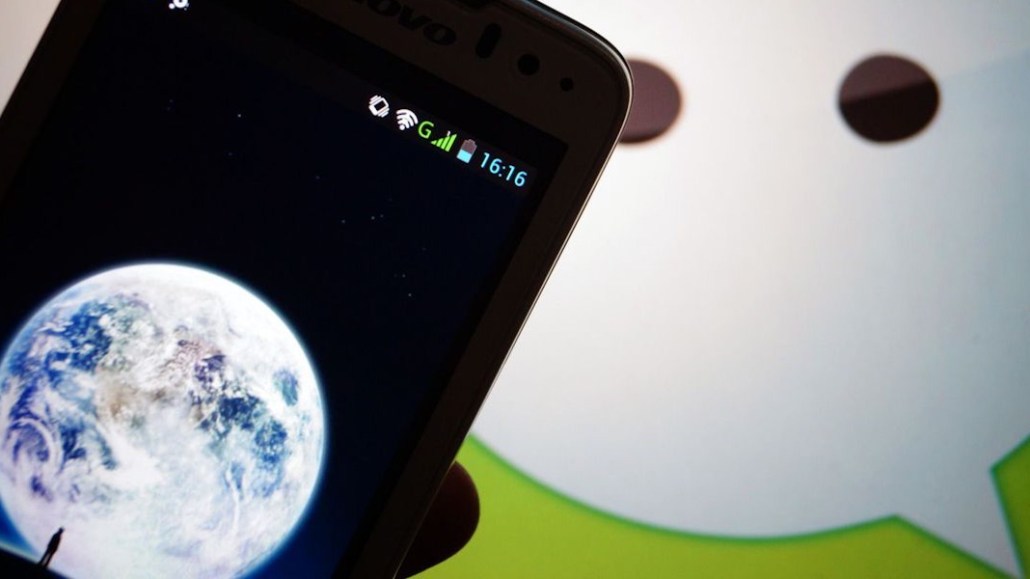
If you live in the U.S., “social payments” is relegated to Venmo and its emoji-powered money transfers.
But compare that relatively thin offering to China’s WeChat, the do-everything messaging app that is the cornerstone of Chinese digital life. WeChat lets users execute peer-to-peer payments, top up their mobile phones, pay utility bills and book plane, train and movie tickets or book a karaoke session – to name just a few things. If China is any indication, social networks and messaging services could be killer apps for money transfer; WeChat is already leading that movement.
“WeChat is kind of a de facto operating system and has massive, massive usage,” said Sean Neville, cofounder and president of bitcoin wallet turned social payments app Circle. “There isn’t anything quite like that in the West.”
Just yet. But when WeChat, or a WeChat-like clone, finally hits the U.S., it’s going to look different. There’s more competition in the U.S., so there will probably be a few players as opposed to one “winner.” And although the U.S. payments system desperately needs an upgrade – sending payments is excruciatingly slow and expensive – it works well enough; how much U.S. customers benefit from paying in new ways with new technologies doesn’t yet outweigh trained behaviors that don’t want to change.


More in Marketing
How Kroger, Giant Eagle and DoorDash are building their agentic AI assistants
Companies are finding that they must deploy practical AI tools that bridge the gap between physical stores and online ordering.
Beauty brand Cakes wants to turn its TikTok virality into an owned media strategy
Cakes is launching Cakes Media to shift from paid TikTok views to a permanent, brand-owned audience as ad costs climb.
Mobile ad giants AppLovin and Unity locked in legal dispute over data collection
AppLovin seeks court order against Unity claiming improper collection of data generated through its business.